
What if the weight of a mortgage you can no longer afford didn't have to end in the public heartbreak of a foreclosure? I understand how suffocating it feels when the phone rings and it's another lender calling about a late payment. Working with a short sale specialist Apple Valley homeowners can trust makes all the difference when you're staring at stacks of complex paperwork. It's exhausting to worry about how a total loss will haunt your credit for the next decade. You want a way out that preserves your dignity, but the path forward often feels like a maze of red tape.
I'm here to show you that you don't have to face the banks alone. I specialize in helping High Desert homeowners navigate these negotiations to sell their property for less than the balance and walk away from the debt. In this article, I'll explain how 2026 California laws, like AB 1542, can speed up lender response times to 45 business days. I'll also preview the steps I take to manage the paperwork and act as your personal shield, ensuring you can finally move forward with peace of mind.
Key Takeaways
- Learn the critical differences between a short sale and foreclosure and how making the right choice helps protect your credit score.
- Discover how a short sale specialist Apple Valley residents rely on can leverage 2026 California laws to speed up lender response times.
- Understand why technical short sale negotiations require a dedicated advocate rather than a general real estate agent.
- Get a clear roadmap for preparing a Short Sale Package that meets strict lender requirements and demonstrates financial hardship.
- Find out how professional guidance can stop the stress of lender calls and help you move forward from a difficult financial situation.
What is a Short Sale and Why Do You Need an Apple Valley Specialist?
A short sale occurs when a lender agrees to accept a payoff that is less than the total amount you owe on your mortgage. If you've been searching for a What is a Short Sale definition, it essentially means the bank is willing to "short" the balance to facilitate a sale and avoid the costs of a foreclosure. For homeowners in the High Desert, this is a strategic path to resolve debt and move forward with their lives. Working with a short sale specialist Apple Valley residents trust is crucial because these transactions require intense negotiation and a deep understanding of local market conditions.
The main goal of a short sale is to satisfy the debt completely. I help you present a case to your lender that proves you cannot sustain the current payments, which encourages them to release the lien. This process isn't just about selling a house; it's about protecting your financial future and preventing the bank from pursuing you for the remaining balance later.
Short Sale vs. Foreclosure: The Long-Term Impact
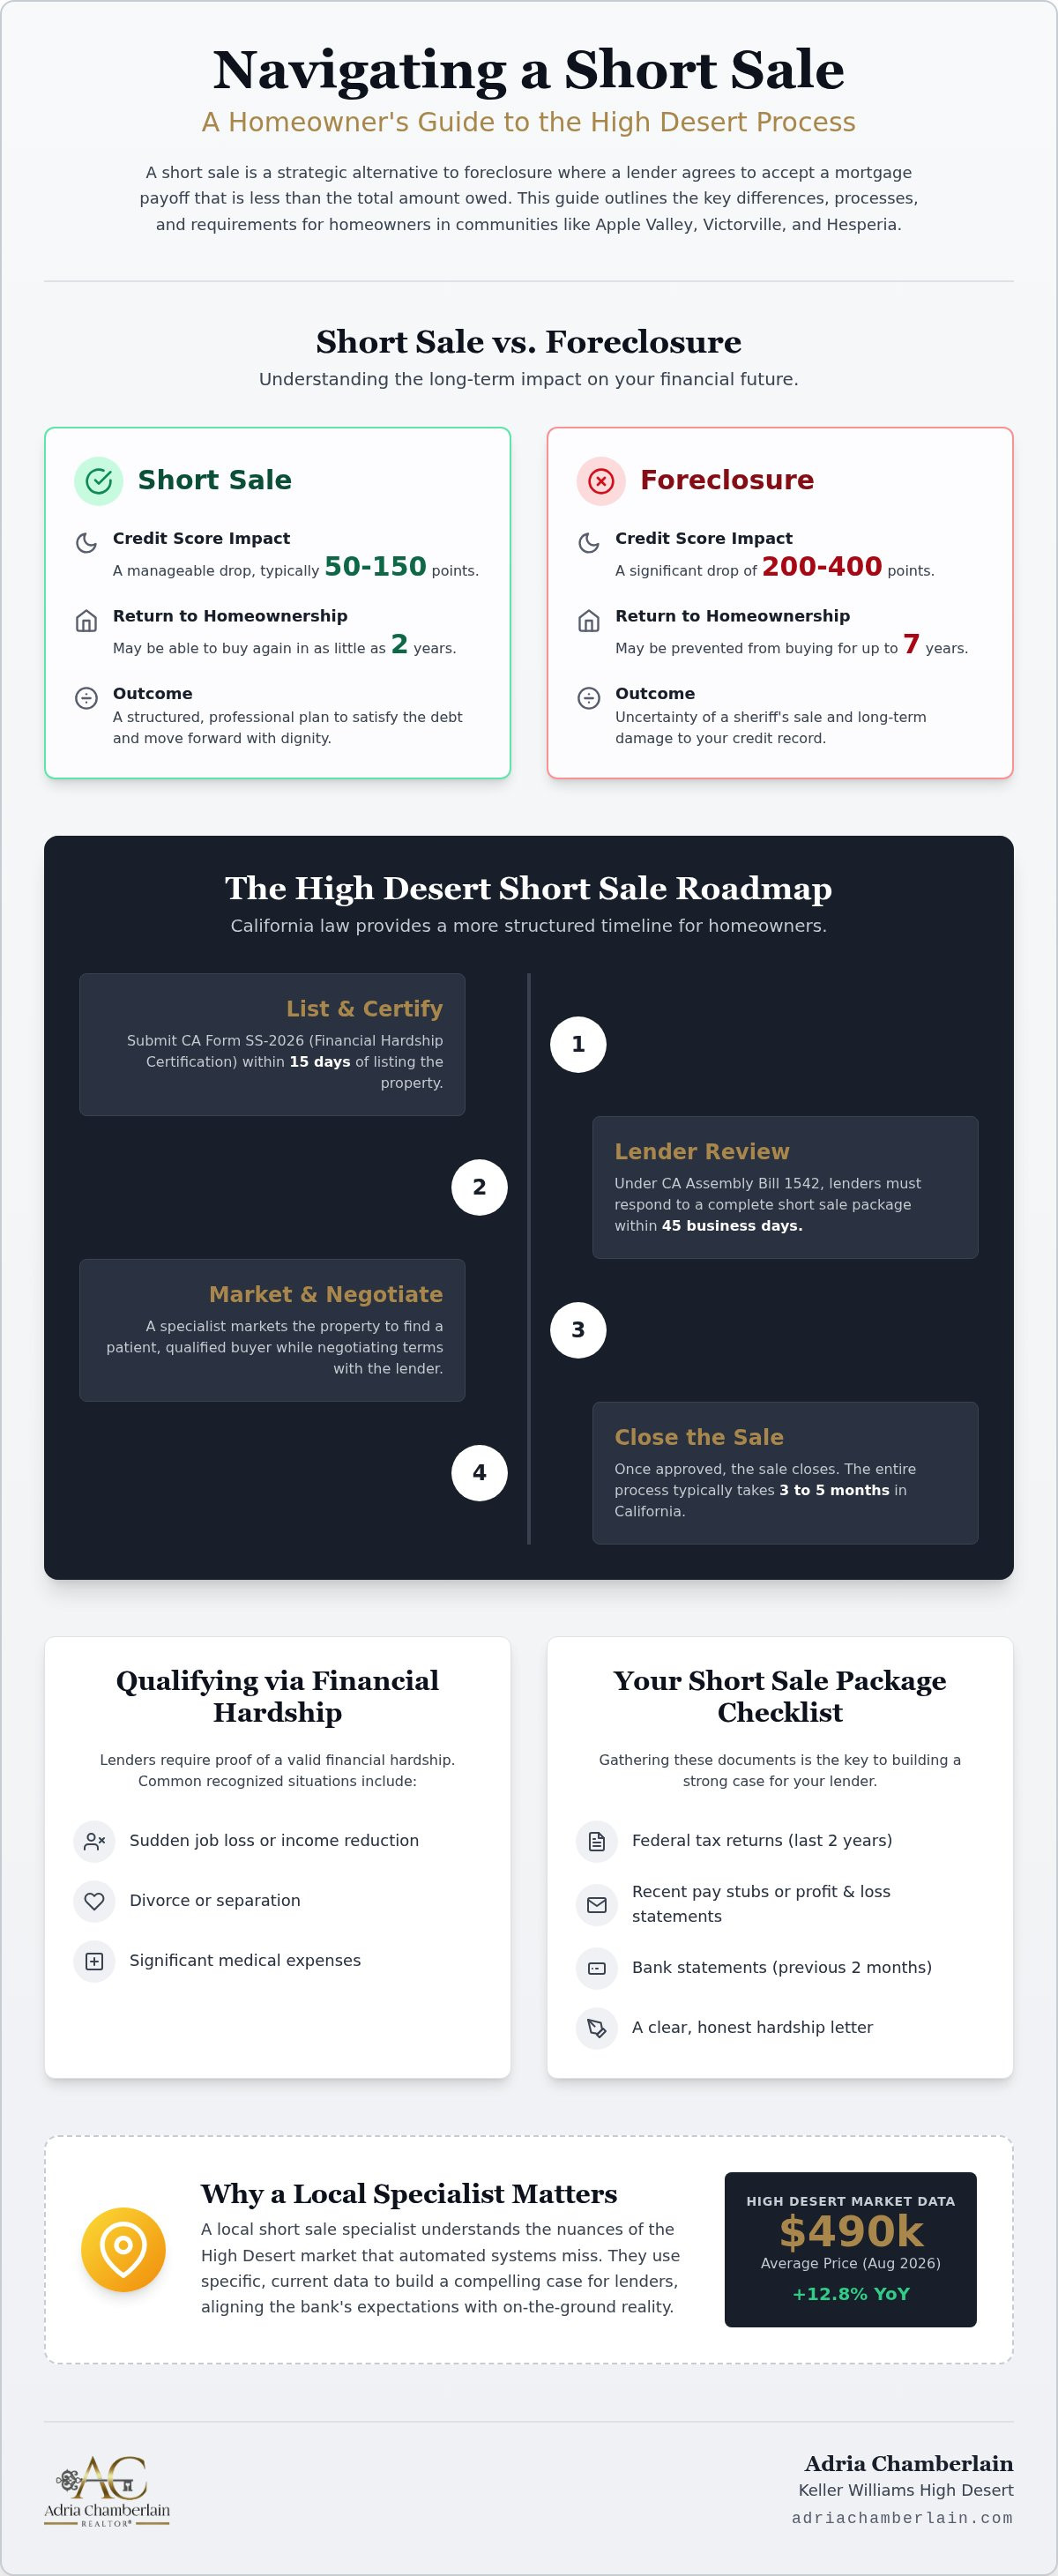
Choosing a short sale over a foreclosure is often the best way to preserve your credit for the future. A foreclosure can stay on your record for years and may drop your credit score by 200 to 400 points. A short sale is generally less damaging, with typical score impacts ranging from 50 to 150 points. This difference is vital when you're ready to rebuild. While a foreclosure might prevent you from buying another home for up to seven years, a short sale often allows you to re-enter the housing market in as little as two years. Taking this proactive step provides immediate emotional relief and replaces the uncertainty of a sheriff's sale with a structured, professional plan.
Why a Local Apple Valley Perspective Matters
Banks often rely on automated data that doesn't capture the reality of our local neighborhoods. An out-of-area agent might not understand why a property in Jess Ranch carries a different value than one in Sycamore Rocks. As of August 2026, the average house price in the High Desert has climbed to $490,000, which is a 12.8% increase year-over-year. I use this specific data to show lenders why your home should be priced a certain way to attract a buyer quickly. Being local means I can personally meet with inspectors and appraisers on-site to advocate for your home's value, ensuring the bank's expectations align with the actual High Desert market.
The Short Sale Process in the High Desert: A 2026 Roadmap
The journey from listing your home to finally closing the deal typically takes between three and five months in California. However, recent changes in the law have provided a more structured timeline for homeowners. Under Assembly Bill 1542, which went into effect on February 1, 2026, lenders are now required to respond to a complete short sale package within 45 business days. This is a massive improvement over the old 90-day standard. To qualify for this expedited review, I help you submit the California Department of Real Estate Form SS-2026, also known as the Financial Hardship Certification, within 15 days of listing your property. This proactive approach ensures we aren't left waiting in limbo while the bank moves slowly.
Initial Assessment and Hardship Qualification
Lenders won't approve a short sale simply because a homeowner wants to move; they require proof of a valid financial hardship. Common situations that banks recognize include a sudden job loss, a divorce, or significant medical expenses. I start our process with a deep dive into your specific financial situation to ensure we can build a strong case for the bank. Gathering the right documentation early is the key to a smooth approval. You'll need to prepare several items for your package:
- Federal tax returns from the last two years
- Recent pay stubs or profit and loss statements
- Bank statements from the previous two months
- A clear, honest hardship letter explaining your current circumstances
Before we put the home on the market, it's vital to have a professional home valuation. If the price is too high, the bank won't see any offers. If it's too low, they'll reject the sale entirely. Finding that precise balance is where my experience as a short sale specialist Apple Valley homeowners trust becomes your greatest advantage.
Marketing the Distressed Property
Marketing a short sale requires a specialized strategy. I list the property with full transparency, ensuring potential buyers and their agents know exactly where we stand with the lender. It's important to find a patient buyer who understands that the bank has the final say on the timeline. While we wait for approval, I act as your shield, managing the frequent check-ins from the lender so you don't have to. If you're feeling overwhelmed by the weight of your mortgage, feel free to reach out for a personalized short sale consultation to explore your options.
Why You Need a Short Sale Specialist Over a General Agent
Many real estate agents focus on high volume sales where transactions close in 30 days or less. Short sales are different; they are administrative marathons that require a technical skill set most general agents don't possess. When you hire a short sale specialist Apple Valley homeowners can rely on, you're getting an advocate who understands the specific language used by a bank's loss mitigation department. I don't just put a sign in the yard and wait for an offer. I manage the constant friction between the buyer's expectations and the lender's rigid requirements to ensure the deal doesn't collapse under its own weight.
General agents often avoid these listings because they involve months of back and forth communication with bank processors who may change mid transaction. I act as the central liaison between the buyer, the seller, and the lender. My job is to keep every party informed and committed, even when the process feels slow. Without this dedicated oversight, small errors in paperwork can lead to a flat rejection from the bank, leaving you right back where you started.
Mastering the Lender Negotiation
Presenting a short sale package to a bank is an art form. It's about telling a financial story that convinces the lender that accepting a lower payoff is more profitable than the high cost of foreclosure. This becomes even more complex if you have a second mortgage or a HELOC. In the High Desert, it's common for properties to have multiple liens. I work to get all lienholders to agree to the sale, often negotiating with different banks simultaneously. I also advocate for a full release of the deficiency judgment. For example, under California's AB 1542, if your household income is less than 150% of the county median, lenders are prohibited from pursuing you for the difference on a primary residence short sale. I help ensure these legal protections are acknowledged during our negotiations.
Mitigating Common Short Sale Pitfalls
A common hurdle is the Broker Price Opinion, or BPO. This is when the bank sends their own representative to estimate your home's value. If their appraisal comes back higher than our actual offer, the bank might reject the deal. I step in to provide local market data, explaining why specific High Desert conditions justify our listing price. Keeping a buyer committed during the 60 to 120 day approval window is another challenge. I maintain a steady rhythm of updates to prevent buyer fatigue, ensuring that when the bank finally says "yes," we still have a ready and willing buyer to cross the finish line.
Preparing Your Short Sale Package: A Step-by-Step Guide
The most critical part of the entire process is the Short Sale Package. This collection of documents acts as your formal application to the lender, and its completeness determines whether the bank even considers your request. I often tell homeowners that the bank is looking for any reason to say no; my job as a short sale specialist Apple Valley owners trust is to make it impossible for them to find one. If the property in question is part of your portfolio of investment properties, the requirements might slightly differ, but the core objective remains the same: proving you can no longer sustain the mortgage debt.
Drafting the Hardship Letter
Your hardship letter is the emotional and logical heart of the package. It shouldn't be a novel, but it needs to clearly state why you can't pay. I advise being direct and honest. You should explain the specific event, such as a job loss, relocation, or medical emergency, that changed your financial situation. Avoid the common mistake of blaming the lender or complaining about market interest rates. The bank's decision-makers want to see that you've tried to resolve the issue and that a short sale is the most profitable outcome for them compared to a foreclosure. A vague letter is a major red flag that can lead to an immediate rejection, so I help you refine your message to be concise and impactful.
The Financial Documentation Checklist
Lenders require full transparency before they agree to lose money on a loan. You'll need to organize a significant amount of paperwork to prove your inability to pay. This typically includes:
- Two years of federal tax returns and W-2s
- An itemized list of all monthly assets and expenses
- Two months of recent bank statements for all accounts
- Recent pay stubs or a profit and loss statement if self-employed
I help you review these documents for completeness before we submit them. Missing a single signature or including an outdated statement can reset the 45-day review clock provided by California's AB 1542. My goal is to ensure your package is decision-ready the moment it hits the processor's desk. This attention to detail prevents the back and forth that often kills deals. If you're ready to start gathering your paperwork, you can contact me for a document checklist to ensure you have everything you need to move forward.
Moving Forward: Your Apple Valley Short Sale Advocate
Deciding to pursue a short sale is a heavy choice, but you don't have to carry that weight by yourself. I'm committed to being more than just a listing agent; I'm your dedicated advocate in a complex system. When you work with a short sale specialist Apple Valley families can lean on, you're choosing someone who handles the aggressive lender calls and the mountain of paperwork on your behalf. My goal is to manage the heavy lifting so you can focus on your family and your next chapter. For many High Desert homeowners, this isn't an end. It's a strategic fresh start that protects your financial future and restores your peace of mind.
Personalized Guidance for High Desert Residents
I believe in a "real people first" approach. Every home in Apple Valley, Victorville, or Hesperia represents a person's life and years of hard work. Since I began my career in 2017, I've focused on providing a supportive, neighborly experience that corporate firms simply can't match. I understand the local nuances of our communities because I live and work here too. I offer a no-pressure consultation where we can sit down and look at your specific needs without any sales tactics. You deserve a clear, honest assessment of your situation, and I'm here to provide that calm expertise with the integrity you expect from a neighbor.
Next Steps Toward Financial Freedom
If you're ready to explore your options, the first step is a confidential meeting. I'll review your mortgage balance, your financial hardship, and the current value of your property to see if a short sale is the right path for you. In the first 48 hours after you decide to move forward, I'll begin the process of contacting your lender to authorize communication and start the file. Taking a proactive step now is the most effective way to avoid the crushing stress of a looming foreclosure.
Federal law requires mortgage servicers to wait until you're more than 120 days delinquent before officially starting the foreclosure process, but you shouldn't wait that long to act. Starting early gives a short sale specialist Apple Valley the time needed to negotiate effectively. This proactive approach gives you the best chance to secure a full release of your debt and move toward a brighter financial horizon. I'm here to help you navigate every step of this journey with confidence and care.
Take Control of Your Financial Future Today
Navigating a distressed property sale is never easy, but you don't have to face the lender's legal department alone. By choosing a short sale, you're taking a proactive step to protect your credit and avoid the long-term impact of a foreclosure. With 2026 California laws now providing faster response times, there's a clear path toward resolving your debt and finding the fresh start you deserve. I'm here to act as your advocate, managing every detail of the negotiation with the calm expertise that only a local neighbor can provide.
As a licensed REALTOR® since 2017 (DRE 02032478) affiliated with Keller Williams High Desert, I've spent years helping residents in Apple Valley and the wider High Desert area through these complex transitions. I'm deeply rooted in this community and committed to your success. If you're ready to stop the stress of lender calls and move forward with dignity, I'm ready to help. Please schedule a confidential short sale consultation with Adria Chamberlain to discuss your options. You've worked hard for your future, and a short sale specialist Apple Valley can help you protect it.
Frequently Asked Questions
What exactly is a short sale specialist and why do I need one in Apple Valley?
A short sale specialist is a real estate professional with specific expertise in negotiating with lenders to accept a payoff that is less than the total mortgage balance. I help Apple Valley homeowners by managing the complex communication with bank loss mitigation departments. This specialized guidance is necessary because general agents often lack the technical knowledge required to handle the 45 day review cycles and specific documentation mandated by 2026 California laws.
Will a short sale stop a foreclosure that has already started?
A short sale can often pause or stop an active foreclosure if the process begins early enough. In California, a foreclosure auction can be postponed by at least 45 days if you provide the trustee with a signed listing agreement from a licensed broker. I work quickly to notify your lender of the listing to seek a stay of the sale, allowing us the time needed to find a buyer and secure bank approval.
How much does it cost the seller to hire a short sale specialist?
Typically, it costs the homeowner nothing out of pocket to hire me for a short sale. Real estate commissions, along with other standard closing costs like escrow and title fees, are usually paid by the lender from the proceeds of the sale. The bank agrees to these costs because a successful short sale is often less expensive for them than completing the entire foreclosure and eviction process in the High Desert.
How long does the average short sale take to close in the High Desert?
Most short sales in our area take between three and five months from the initial listing to the final closing date. Under California's AB 1542, lenders are now required to respond to a completed package within 45 business days. This structure helps move the process faster than in previous years, though the total timeline still depends on how quickly a qualified buyer is found and how many liens are attached to the property.
Can I stay in my home during the short sale process?
You can generally remain in your home until the sale officially closes and the title is transferred to the new owner. This allows you to maintain the property while I market it to potential buyers. Staying in the home also helps prevent issues like vandalism or maintenance problems that often occur with vacant properties in neighborhoods throughout Apple Valley, Hesperia, and Victorville while we wait for the lender's final decision.
What is a deficiency judgment and can a short sale prevent it?
A deficiency judgment is a court order allowing a lender to collect the remaining balance if your home sells for less than you owe. A short sale can prevent this if negotiated correctly. In California, Code of Civil Procedure §580e prohibits lenders from pursuing these judgments on 1 to 4 unit residential properties after an approved short sale. I advocate for a full release of liability in every negotiation to protect your future income.
Do I have to pay taxes on the forgiven debt in a short sale?
Whether forgiven debt is considered taxable income depends on your specific financial situation and current state or federal tax laws. While I provide guidance on the short sale process, I am not a tax professional. I always encourage Apple Valley homeowners to consult with a qualified CPA or tax attorney to understand how a short sale might impact their tax filings, especially regarding the 1099-C form issued by lenders after closing.
What are the common reasons a bank might reject a short sale offer?
Banks most often reject offers if the Short Sale Package is incomplete or if the offer price is significantly below their internal appraisal. Other reasons include a lack of documented financial hardship or the presence of a second mortgage holder who refuses to cooperate. As a short sale specialist Apple Valley residents trust, I work to mitigate these risks by reviewing all documents for accuracy and providing local market data to justify the price.


